AEP Plans $5 Billion in Grid Upgrades for Piketon Data Center
AEP's new $100 billion investment plan includes three proposed 765-kV lines for the Ohio campus. Its filings show how the connection would arrive in stages; PJM's queue shows the stages of generation projects across AEP's PJM transmission footprint.
AEP raised its five-year investment plan to $100 billion for 2027–2031 on October 28. The clearest picture of what that money builds is one customer in southern Ohio: a proposed 10.4 GW data center campus at Piketon, with about $5 billion of transmission work attached to it in AEP's quarterly filing.
The campus would connect in stages. The first 800 MW would run on existing transmission. Three new 765-kilovolt lines would then each add approximately 3,200 MW, targeted for the ends of 2028, 2029 and 2030, subject to regulatory approval.
A 50-mile proposed line from Gavin to Baku#
AEP has filed a siting application for Baku–Gavin: roughly 50 miles of new 765-kV line through Pike, Jackson and Gallia counties. The map uses AEP's own alignment and station locations, drawn over existing transmission. Select the route to follow it across the region, or a station to see what surrounds it.
The other lines are less settled. Hanging Rock–Baku has published study alternatives and no selected route. AEP also identifies a feasibility study in Pike, Ross and Pickaway counties, but publishes no alignment for the third line in the filing.
The first 800 MW would use existing transmission#
The 10.4 GW connection plan arrives in phases
Piketon campus · cumulative planned load-serving capacity in GW · AEP's expected schedule
Initial phase
0.8 GW
AEP expects to serve the first 800 MW using existing transmission infrastructure. The filing gives no initial service date. Each later phase depends on the required approvals and construction.
Source: AEP Form 10-Q, filed October 28, 2026, p. 10. Columns add the disclosed transmission phases. They show neither electricity generation nor observed campus consumption. Select a column to read the phase.
Source: AEP third-quarter 2026 Form 10-Q, Piketon Transmission Project, printed page 10. Initial 800 MW on existing transmission plus three new 765-kV lines of approximately 3.2 GW each. End-of-year targets are conditional on regulatory approvals and construction; no initial service date is specified. The graphic adds the disclosed phases, not measured campus demand or operating generation.
The schedule shows how far a customer commitment runs ahead of the wires. It also raises the supply question. Ask the Grid's October 30 snapshot of PJM's public queue lists 24 entries totaling 3.68 GW under construction with AEP as transmission owner. Solar is 64.4% of that capacity, and far more sits earlier in the pipeline, in engineering and procurement.
The queue spans AEP's PJM footprint across several states and includes independent developers. It shows regional supply coming, not resources contracted to Piketon.
The campus and its power plants have separate development paths#
The campus is planned on part of the former Portsmouth gaseous diffusion plant site and nearby private land. The Department of Energy's March 20 announcement described roughly 10 GW of data center development and planned generation of at least 9.2 GW of natural gas. AEP's October filing puts the campus at 10.4 GW.
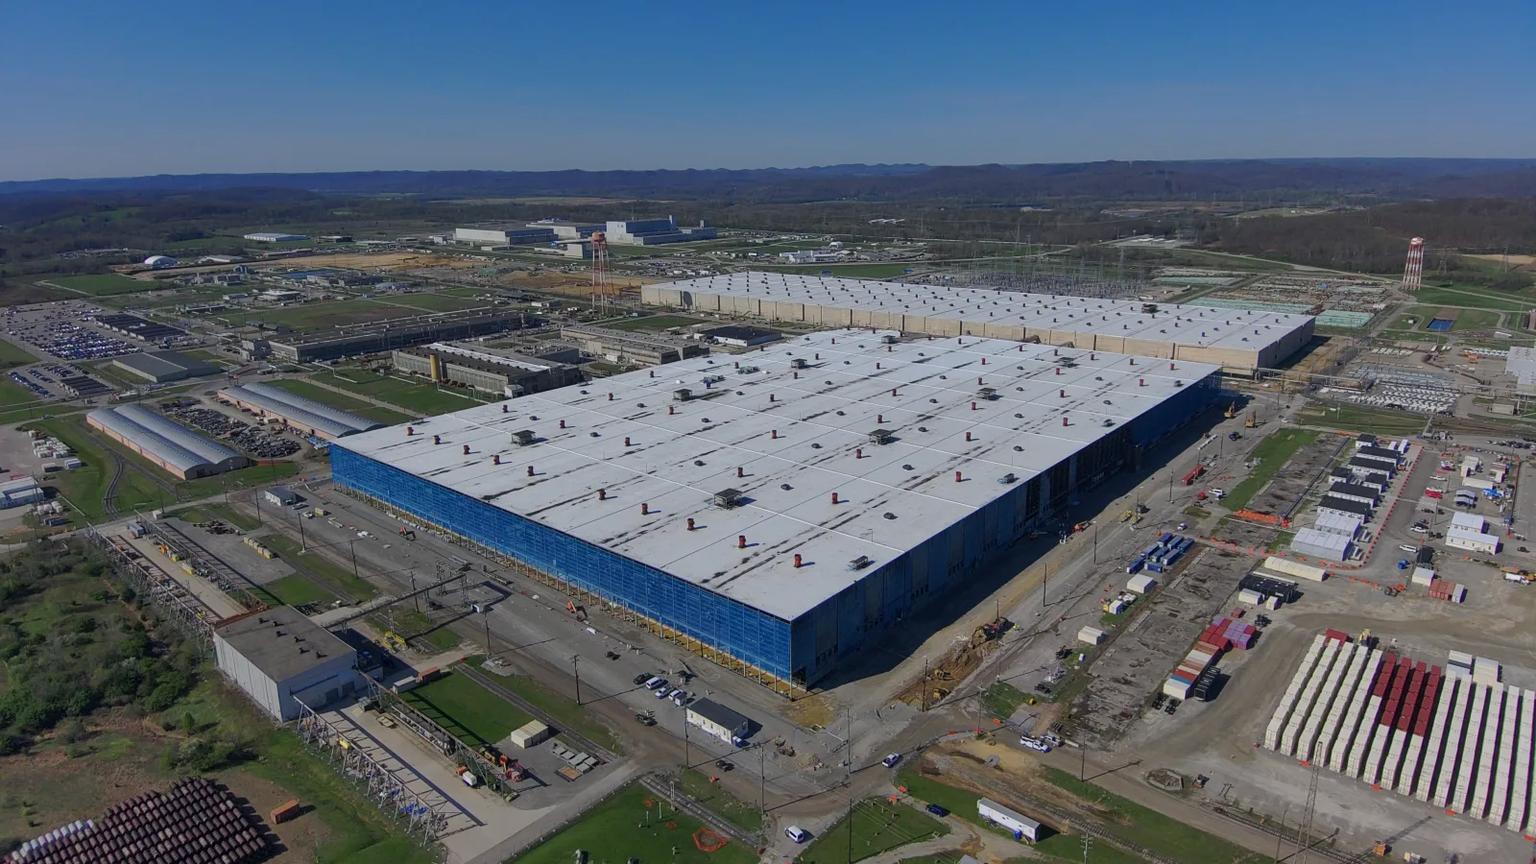
The X-333 cleanup building at the Portsmouth site, pictured in a June 30 DOE update. Photo: U.S. Department of Energy. Cropped and resized.
The gas plants belong to someone else. In its September 21 registration statement, SB Energy said a SoftBank affiliate would develop the neighboring 9.2 GW of gas generation and that SB Energy did not expect to own or operate it. As of that prospectus the plants were not financed, built or contracted. The filing also separated 8 GW of critical IT capacity from roughly 10 GW of gross power load, so the September and October figures count different things.
In August, AEP's Ohio subsidiaries and the customer signed definitive agreements for the three transmission lines. The initial 800 MW is about 7.7% of the 10.4 GW campus; the three additions supply the other 9.6 GW. Those completion dates are AEP's targets for the wires, not dates by which the campus will be drawing full power.
One line already has a public route process. AEP Ohio's September 22 notice describes the Hanging Rock–Baku 765-kV project, linking an existing station in Lawrence County to a proposed station in Pike County. AEP will seek Ohio Power Siting Board approval, with construction proposed from late 2027 through 2029.
AEP's study map shows alternatives for a new line, rebuilt segments and relocations near the existing network. The reconstruction above keeps those paths, registered against Ohio Department of Transportation road geometry, with about 1 km of positional uncertainty. AEP will choose one route after public feedback and feasibility work. Not every alternative will be built.
AEP’s original study map and legend
Route under study · no final alignment selected
Hanging Rock–Baku: the study alternatives
AEP's original map distinguishes new-line alternatives, rebuilds and relocations. Expand the map to inspect the segments and its full legend.
Source: AEP Transmission · virtual open house · retrieved October 30, 2026
AEP’s 84 GW includes different kinds of customer commitment#
AEP's headline demand number reaches well beyond Piketon. Its earnings presentation splits 84 GW of incremental contracted load through 2031 into 31 GW in PJM, 7 GW in SPP and 46 GW in ERCOT. Ohio Power accounts for 23 GW of the total.
AEP's 84 GW spans different contracts and markets
AEP incremental contracted load through 2031 · company-reported figures in GW
Source: AEP Q3 2026 earnings presentation, slides 18 and 27. Company figures are rounded. These are commitments for future demand, with different contractual terms. The market split is a separate classification of the same 84 GW.
Source: AEP third-quarter 2026 earnings presentation, slides 18 and 27. AEP reports 35 GW under firm take-or-pay electric service agreements, 3 GW under PJM/SPP letters of agreement and 46 GW under ERCOT letters of agreement. The separate market split is 31 GW PJM, 7 GW SPP and 46 GW ERCOT. Rounded company figures; contracted future demand is not observed load or generation capacity.
How firm the commitments are varies. About 35 GW is under firm, take-or-pay electric service agreements, 3 GW under letters of agreement in PJM and SPP, and 46 GW under letters of agreement in ERCOT. Data centers, including cryptocurrency operations, are 92% of the mix.
The capital plan splits roughly $37 billion to transmission, $36 billion to generation and $22 billion to distribution. Piketon's lines are one slice of the transmission share.
The generation queue is large, but its stages differ#
The latest complete queue snapshot available to Ask the Grid on October 30 lists, with AEP as transmission owner, 56 active entries totaling 11.35 GW, 64 in engineering and procurement totaling 11.89 GW, and 24 under construction totaling 3.68 GW. Another 15 entries totaling 2.09 GW are partly in service with construction continuing.
Construction is a smaller part of AEP's PJM generation pipeline
PJM generation queue · transmission owner AEP · October 30, 2026 snapshot
Under Construction · technology
24 entries · 3.68 GW requested
Source: PJM queue, through Ask the Grid. Counts are queue entries; requested MW is not accredited or delivered supply. Partially operating entries include capacity already in service. The AEP transmission-owner filter covers PJM, while AEP’s corporate demand announcement covers several markets.
Source: PJM generation interconnection queue via Ask the Grid, October 30, 2026 snapshot. Counts are unique queue entries, not necessarily distinct physical projects. Capacity is requested MW; entries marked partially in service include capacity already operating. These are projects connecting to AEP transmission in PJM, not an inventory of AEP-owned generation or supply reserved for Piketon.
Solar is 18 of the 24 under-construction entries, or 2,372.5 MW. The rest are one 480 MW gas project, two solar-and-storage entries totaling 330 MW, two wind entries totaling 300 MW and one 200 MW storage entry. In engineering and procurement, solar alone is 7.77 GW of 11.89 GW.
Ohio holds 11 under-construction entries totaling 1.31 GW and 22 engineering-and-procurement entries totaling 5.39 GW. The state line says little about who those plants serve, since power flows across the interconnected network.
Technology matters as much as megawatts. Solar follows daylight and weather, storage shifts energy but runs out, and gas depends on fuel and unit availability. Requested MW is not hourly output or reliability value, and adding them into one firm-supply number would hide those differences.
So the queue is a regional pipeline, not a Piketon supply balance. AEP's 84 GW covers three markets; the queue covers one transmission owner's footprint; the neighboring gas plants follow their own path. What the queue does show is more capacity waiting in engineering and procurement than under construction, with solar the largest technology in both.
Customer payments extend 20 years after each line enters service#
AEP's filing says the customer would bear the project's costs through an Ohio Power retail service agreement, subject to approvals. Payments would run 20 years from each line's in-service date, and the customer would post full collateral for equipment commitments made before approvals.
Approvals are still ahead from PJM, the Public Utilities Commission of Ohio and FERC, and route approval is a separate step. The agreement, the approved tariff treatment, the transmission build and the campus's actual demand each settle a different part of who pays and who gets served.
The next milestones are approvals and construction#
PJM's queue is worth rechecking as those dates arrive. Entries move into construction, begin partial service, reach full service or withdraw, and those moves show how supply changes while AEP builds. The broader PJM capacity story covers how much reliability the market's supply provides; Piketon adds a concrete customer and a transmission schedule to it.
The next date is close. AEP's Baku–Gavin project page lists a November 5 adjudicatory hearing on the proposed 765-kV line under Ohio Power Siting Board case 26-0426-EL-BTX. AEP says the application was certified complete on August 28. The hearing and the board's decision will move the route toward approval, which has not happened yet.
Sources and method#
Project terms come from AEP's October 28 Form 10-Q, printed page 10. Load and capital-plan figures come from the earnings release and presentation, slides 18 and 27. Planned generation figures come from DOE's March 20 announcement and keep the September 21 status disclosed by SB Energy. Dollar amounts are company budgets, and future dates are proposed or expected.
Proposed-route geometry and the Baku and Gavin station positions come from the KML files loaded by AEP's public project map, retrieved October 30, without interpolation or snapping to station pins. Existing-line context comes from Ask the Grid's infrastructure layers. The route is a proposal under case 26-0426-EL-BTX. Hanging Rock–Baku study segments are extracted from the vector figure in AEP's virtual open house, retrieved October 30, and registered to official ODOT highway geometry. Road-shape alignment and four named junction checks support the placement; independent station-symbol checks differ by about 0.55–0.78 km. The map therefore allows roughly 1 km of positional uncertainty and does not snap the segments to the station points. The original figure and legend sit beside the map. The area overview identifies the northern feasibility study. Neither study selects a route.
Queue calculations use PJM's public generation interconnection queue, mirrored in Ask the Grid Data, at the single October 30, 2026, 11:00:29 UTC snapshot. The filter is transmission owner AEP, not generator ownership or a supply contract. Each queue ID is counted once, and separate IDs can be phases or entries at one site. Requested capacity is the source's capacity_mw field. Hybrid solar-and-storage capacity stays as one category. Partly in-service entries keep their full requested MW, including capacity already operating. The proposed-completion field is empty for these groups, so no commissioning dates are inferred.